Best Housing Society in Rawalpindi: A Smart Money Plan for 2026
Buying property is one of the biggest financial decisions most people ever make, and the way you budget for it matters just as much as which plot you ultimately choose. If you’re approaching the market the way a disciplined investor approaches any major purchase — with a plan, not just excitement — you’re already ahead of most buyers hunting for the best housing society in Rawalpindi this year.
This guide treats a plot purchase the way a financial coach would: start with the numbers, understand the full cost of ownership, then layer in location and lifestyle factors once the budget framework is solid. We’ll cover realistic cost planning, how structured payment plans actually work, and the financial discipline required to see a plot purchase through from booking to possession.
Start With the Full Cost, Not Just the Plot Price
The advertised plot price is only the headline number. A realistic budget needs to account for transfer fees, membership and development charges, utility connection deposits, and eventually construction costs once you’re ready to build. Buyers who budget only for the plot price routinely find themselves short of cash exactly when a critical installment is due.
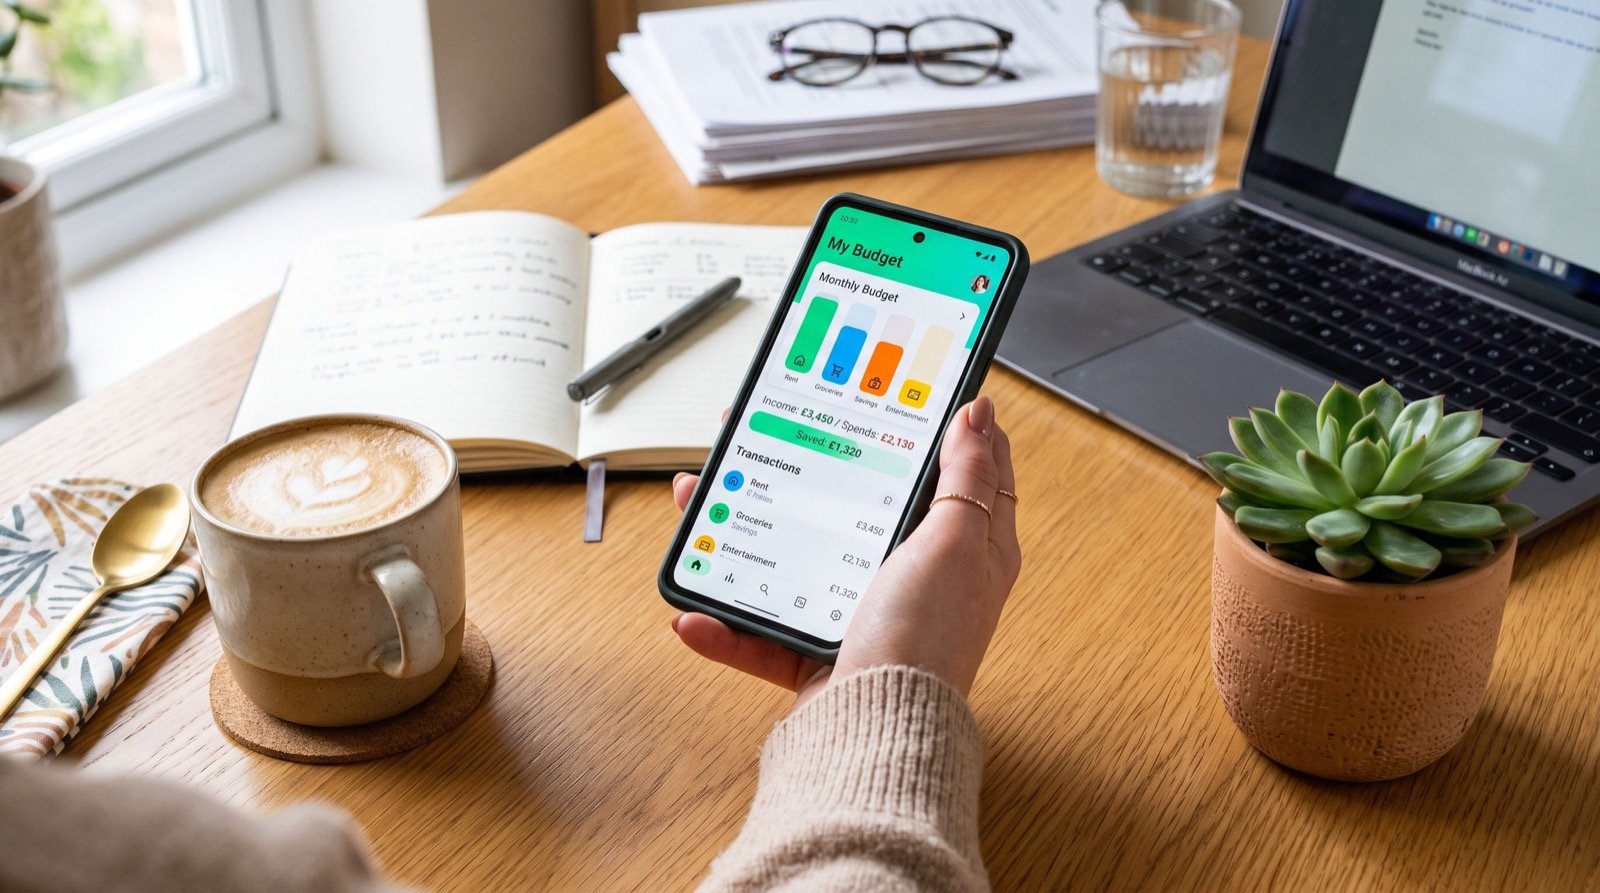
A Simple Budgeting Framework
- Plot price plus a 10–15% buffer for fees and charges
- A separate, untouched fund for construction once possession is granted
- An emergency cushion equal to at least one installment amount
- A clear personal deadline for when you need possession, working backward from that date
How Structured Payment Plans Actually Work
Most established developments spread payments across a down payment, a series of quarterly or semi-annual installments, and a final possession-linked payment. Understanding the exact structure before booking prevents the common mistake of assuming monthly flexibility that the contract doesn’t actually offer.
Reviewing the detailed Silver City payment Plan structure before committing shows exactly how a well-organized installment schedule should be laid out — clear dates, fixed amounts, and a transparent possession timeline rather than vague promises about “flexible terms.”
Fixed vs Flexible Installment Structures
| Feature | Fixed Installment Plan | Flexible/Custom Plan |
|---|---|---|
| Payment predictability | High — same amount each period | Lower — can vary by negotiation |
| Best suited for | Salaried buyers with steady income | Business owners with variable cash flow |
| Risk of missed payment | Lower if budgeted correctly | Higher without strict personal tracking |
| Developer preference | Usually the default offering | Sometimes available on request |
| Total cost over time | Typically lowest | May include a negotiated premium |
It also helps to map out worst-case scenarios before you ever sign a booking form. What happens to your budget if your income drops for one quarter? Could you cover an installment from your emergency cushion without touching the construction fund? Buyers who run this stress test on paper, before any money moves, almost always negotiate better terms because they know exactly which clauses matter most to their specific situation.
Choosing the Right Society Once Your Budget Is Set
Only after your financial framework is locked in should location and amenities enter the decision. A society that’s slightly further from the city center but offers a payment plan matching your actual cash flow is a better financial decision than a prestigious address that strains your budget every quarter.
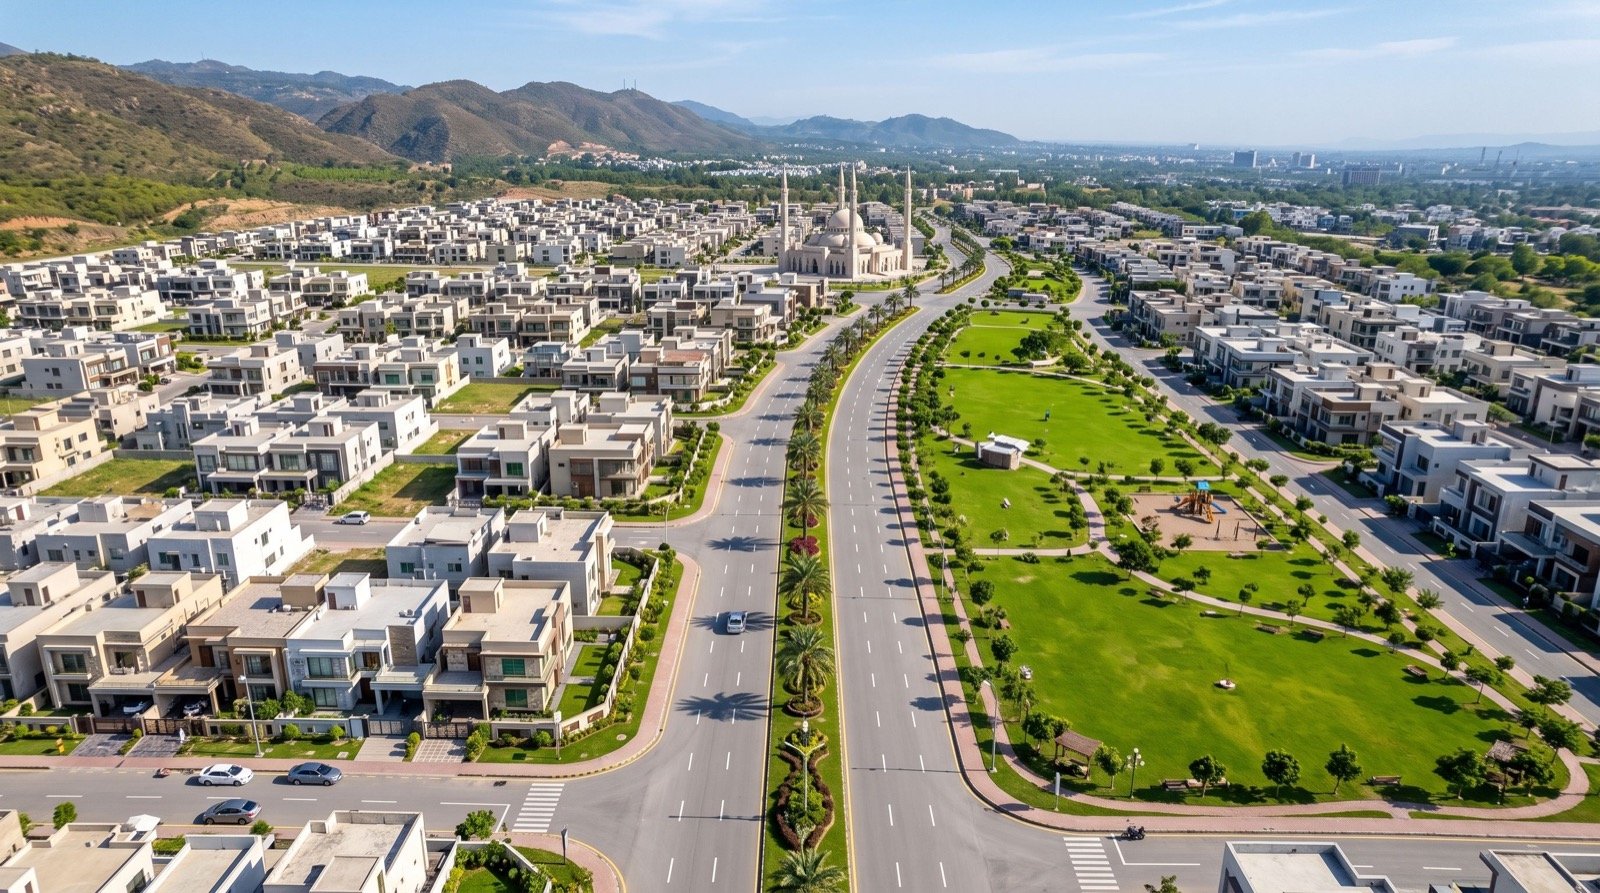
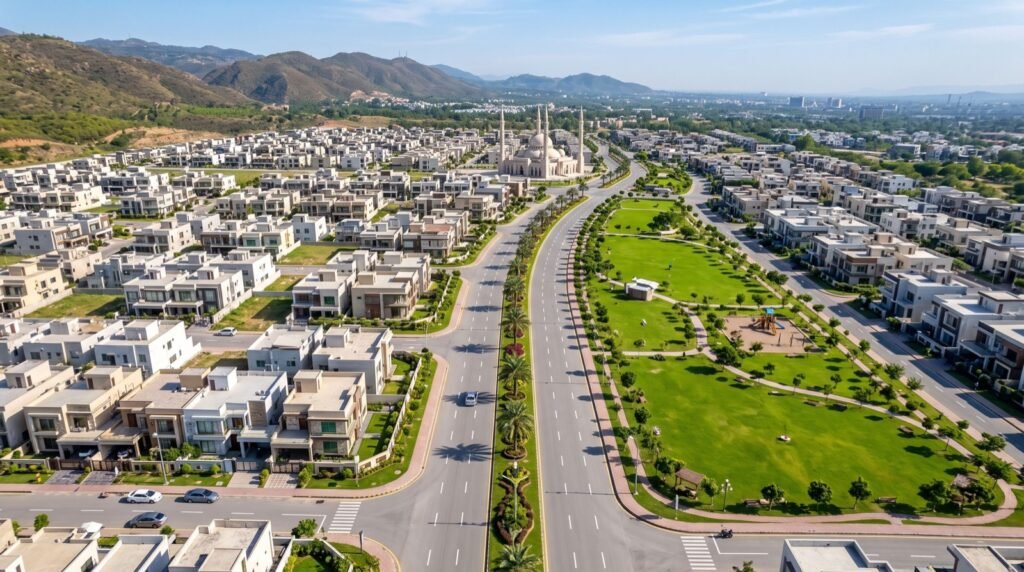
When people search for the Best Housing Society in Rawalpindi, the strongest candidates typically combine confirmed development authority approval, a visibly progressing construction timeline, and payment terms that don’t require buyers to overextend themselves to keep up.
Questions to Ask the Sales Office About Money, Specifically
Before signing, ask directly: What happens if I miss one installment? Is there a grace period? Does the final payment amount change if possession is delayed on the developer’s end? Clear, confident answers to these questions are a good signal; vague or defensive answers are not.
The Discipline Side of Property Investment
Securing a plot is the easy part emotionally — the showroom visit, the brochure, the excitement of choosing a block. Making every installment on schedule for two to four years straight is the part that actually determines whether the investment pays off. Treat each installment like a recurring, non-negotiable expense in your personal budget, the same way you’d treat a loan payment, rather than something to cover “if there’s money left over” that month.
One Practical Tip for Staying on Schedule
Set up a dedicated sub-account or separate savings pocket that receives a fixed transfer the moment your income arrives, timed specifically ahead of each installment due date. Buyers who pay from whatever happens to be left in a general account at month’s end miss payments far more often than those who isolate the installment amount the day they get paid. This single habit shift prevents more missed-payment penalties than any amount of willpower alone.
Financing Context: What the Numbers Say in 2026
Housing finance availability continues to shift with broader monetary policy. Reviewing current lending benchmarks through the State Bank of Pakistan helps buyers understand whether a bank-financed purchase makes more sense than a pure developer installment plan in the current rate environment. Property tax and transfer valuation details are published by the Federal Board of Revenue, which buyers should check before finalizing their total cost projection.
Getting a second opinion from reliable local experts who understand both the real estate side and the financial planning side of a plot purchase can help you stress-test your budget against installment schedules before you’re legally committed to a multi-year payment plan.
Frequently Asked Questions
How much income should I have before committing to a plot payment plan?
A common rule of thumb is to keep total installment obligations under roughly a third of your monthly income, leaving room for living expenses, savings, and unexpected costs without straining your finances.
What happens financially if I miss an installment?
Most developers charge a late fee or penalty interest, and repeated missed payments can risk cancellation of your allotment, so always confirm the specific grace period and penalty structure in writing before signing.
Is it smarter to pay in cash or use an installment plan?
Cash buyers sometimes receive a discount, but installment plans let you preserve liquidity for construction and emergencies, so the right choice depends on your overall financial picture, not just the headline discount.
Should I buy now or wait for prices to settle in 2026?
Timing the market perfectly is nearly impossible. A financially disciplined buyer who verifies legal status and budgets properly is generally better off buying when the numbers work for their situation than waiting indefinitely for a theoretical better moment.
Final Thoughts
A plot purchase succeeds or fails on the strength of the budget behind it just as much as the location in front of it. Build your full-cost framework first, understand the installment structure in detail, and set up the payment habits that keep you on schedule for years, not just months. Once your numbers are solid, reach out to the sales office this week to lock in current pricing before the next revision.