Cash App Guide for 2026: Fees, Limits, and Smarter Transfers
Peer-to-peer payment apps have become as routine as texting, and Cash App remains one of the most widely used. But plenty of users still overpay in fees, hit unexpected limits, or miss features that could make their money move faster and smarter. This Cash App guide for 2026 covers exactly how the fees work, how to raise your limits, and how to avoid the mistakes that cost people real money every month.
How Transfers Actually Work
When you send money through a peer-to-peer app, you typically have two options: a standard transfer that is free but takes one to three business days, or an instant transfer that lands in minutes but comes with a fee, usually between 0.5% and 1.75% depending on the amount and the receiving account.
For most routine transfers, like splitting a dinner bill or paying back a small loan from a friend, the standard free option makes sense. Reserve the instant option for genuine emergencies, like covering rent before a late fee kicks in.
Understanding Sending and Receiving Limits
New accounts typically start with lower sending and receiving limits until identity verification is completed. Once you verify your identity with a full name, date of birth, and the last four digits of your Social Security number, limits increase significantly.
- Unverified accounts usually cap sending at a few hundred dollars within any 30-day period.
- Verified accounts can typically send several thousand dollars per week and receive unlimited amounts.
- Business accounts often have separate limit structures designed for higher transaction volume.
If you are regularly hitting your limit, verifying your identity is almost always the fastest fix, and it usually takes only a few minutes inside the app.
A Step-by-Step Cash App Guide to Getting Started Safely
- Download the app and create an account using a strong, unique password.
- Verify your identity immediately to unlock higher limits and additional features.
- Enable two-factor authentication and set a security PIN or biometric lock.
- Link your bank account using the official in-app connection rather than entering routing numbers found elsewhere.
- Start with a small test transfer to a trusted contact before relying on the app for larger payments.
A thorough Cash App guide will always emphasize this verification step early, because it protects both your money and your ability to use higher limits when you actually need them.
Common Fees Compared
| Transaction Type | Typical Fee | Speed |
|---|---|---|
| Standard bank transfer | Free | 1-3 business days |
| Instant transfer | 0.5%-1.75% | Minutes |
| Credit card payment | ~3% | Instant |
| ATM withdrawal (in-network) | Free with qualifying deposits | Instant |
How Can You Avoid Unnecessary Fees?
The simplest way to avoid fees is to plan transfers a day or two ahead whenever possible, so you never need to pay for speed. Beyond that, a few habits make a real difference.
- Set up qualifying direct deposits where available, which often unlocks free ATM withdrawals and other fee waivers.
- Avoid funding transfers with a credit card unless necessary, since that typically carries the highest fee of any option.
- Check your account’s fee schedule periodically, since providers occasionally adjust rates.
Staying Safe From Scams
Peer-to-peer apps are a common target for scammers because transfers are fast and difficult to reverse. The Federal Trade Commission warns that payment app scams often involve someone posing as a buyer, seller, or even a bank representative urging an urgent transfer (consumer.ftc.gov, 2026).
Follow these rules to stay protected.
- Only send money to people you personally know and trust.
- Never send a “test” payment to verify someone else’s account, a common scam setup.
- Be suspicious of anyone claiming to be customer support who asks you to transfer money to “secure” your account. No legitimate support team will ever ask this.
- Double-check usernames and phone numbers before confirming any transfer, since similar-looking profiles are a frequent scam tactic.
Pairing Transfers With a Broader Money Strategy
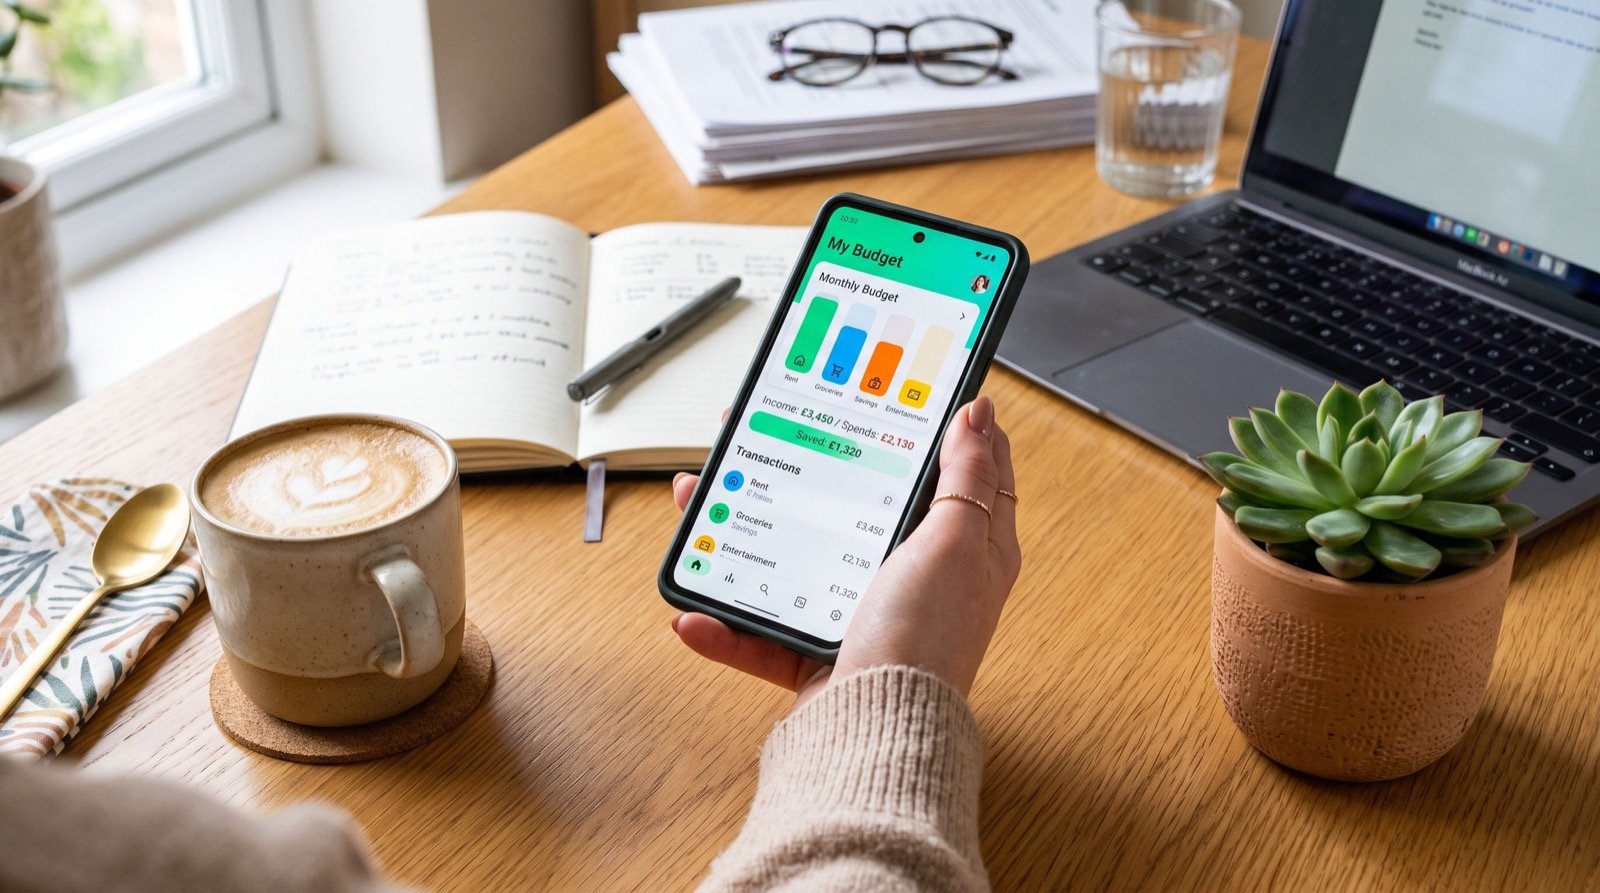
Cash App and similar tools work best as one piece of a bigger financial picture. Combine fast peer-to-peer transfers with a dedicated budgeting app, and review your overall spending using a short list of personal finance tips each month. Relying on any single app for your entire financial life usually leaves gaps in visibility.
Using Cash App for Small Business Transactions
Many freelancers and small business owners now accept peer-to-peer payments from customers as a quick alternative to traditional invoicing. If you plan to use a payment app for business income rather than personal transfers, a few extra considerations apply.
- Separate personal and business activity. Mixing client payments with personal transfers makes bookkeeping and tax time far more complicated than it needs to be.
- Understand reporting thresholds. Payment platforms are required to report business transaction volume above certain thresholds to tax authorities, so keep accurate records throughout the year rather than reconstructing them in April.
- Factor fees into your pricing. If a platform charges a percentage for instant transfers or card-funded payments, build that cost into what you charge clients so it does not quietly eat into your margin.
Treating a payment app as a lightweight point-of-sale tool works well for low-volume side income, but once transaction volume grows, it is worth pairing it with dedicated bookkeeping software to stay organized.
What to Do If Your Account Gets Flagged or Frozen
Payment apps occasionally freeze accounts temporarily when they detect unusual activity, such as an unusually large transfer or a sudden spike in transaction volume. This is typically an automated fraud-prevention measure rather than a sign you did anything wrong.
If this happens, do not panic and do not attempt to work around it by opening a second account, which often makes resolution harder. Instead, contact official in-app support directly, have your identification documents ready, and respond promptly to any verification requests. Most legitimate freezes resolve within a few business days once your identity and the transaction are confirmed.
Frequently Asked Questions
How long does a standard Cash App transfer take in 2026?
Standard transfers to a linked bank account typically take one to three business days and do not carry a fee. Instant transfers land within minutes but include a small percentage-based fee.
What happens if I exceed my sending limit?
The app will block additional transfers until the next limit cycle resets or until you complete identity verification, which usually raises your limit substantially.
Is it safe to link my main bank account?
Yes, as long as you link it through the app’s official, encrypted connection process rather than sharing your login credentials anywhere else. Enable two-factor authentication for extra protection.
Can I get my money back if I send it to the wrong person?
Peer-to-peer transfers are difficult to reverse once completed. Always double-check the recipient’s details before confirming, and contact support immediately if you notice a mistake.
Final Thoughts
A reliable Cash App guide in 2026 comes down to three habits: verify your identity early, understand exactly when fees apply, and stay alert to scam tactics that specifically target fast, hard-to-reverse transfers. Get those three right, and peer-to-peer payments become one of the most convenient tools in your financial routine rather than a source of stress.
The same careful, research-first approach applies to bigger investments, like modernizing a business location. Before committing to a major upgrade, working with reliable local experts helps you avoid costly mistakes, just as verifying a transfer avoids a lost payment.